Zhang, Zihao Author
Biography not available.
Browse all ART CRITICISM books
Browse all Ashworth books
Browse all FOLKLORE books
Browse all GARDENS books
Browse all GRAPHIC NOVELS books
Browse all Hamilton books
Browse all HISTORY - MEDIEVAL books
Browse all HUMOUR books
Browse all Juvenile Fiction : Biographical - Other books
Browse all Juvenile Fiction : Historical - Other books
Browse all Juvenile Fiction : Legends, Myths, & Fables - Other books
Browse all Juvenile Fiction : People & Places - Other books
Browse all Juvenile Fiction : People & Places - United States - Other books
Browse all Juvenile Fiction : Religious - Other books
Browse all Juvenile Nonfiction : History - Other books
Browse all Juvenile Nonfiction : Mathematics - Advanced books
Browse all Juvenile Nonfiction : People & Places - Other books
Browse all Juvenile Nonfiction : People & Places - United States - Othe books
Browse all KINDRED books
Browse all LITERARY STUDIES books
Browse all LONDON books
Browse all Lozada books
Browse all Medical : Nursing - Mental Health books
Browse all MIND books
Browse all MUSEOLOGY books
Browse all NON-CLASSIFIABLE books
Browse all NONLINEAR SCIENCE books
Browse all Ormonde books
Browse all POPULAR SCIENCE books
Browse all RELIGIOUS STUDIES books
Browse all SPIRIT books
Browse all SPORT books
Browse all TRAVEL WRITING books
 Out of Stock
Paperback · ISBN 9781009707114
Inclusive of GST and other taxes
Arriving at your doorstep in 10-15 days
Our logisitcs team will make sure everyitem is delivered safely
| ISBN | 9781009707114 |
|---|---|
| Publisher | Cambridge University Press |
| Publication date | October 2025 |
| Language | English |
| MRP | £18.00 GBP |
| Page count | 184 |
| Item weight | 56 g |
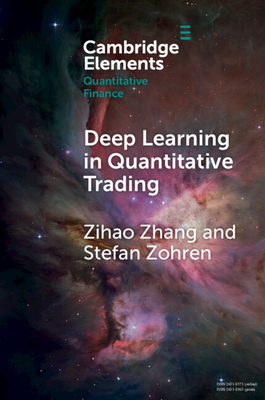
This Element provides a comprehensive guide to deep learning in quantitative trading, merging foundational theory with hands-on applications. It is organized into two parts. The first part introduces the fundamentals of financial time-series and supervised learning, exploring various network architectures, from feedforward to state-of-the-art. To ensure robustness and mitigate overfitting on complex real-world data, a complete workflow is presented, from initial data analysis to cross-validation techniques tailored to financial data. Building on this, the second part applies deep learning methods to a range of financial tasks. The authors demonstrate how deep learning models can enhance both time-series and cross-sectional momentum trading strategies, generate predictive signals, and be formulated as an end-to-end framework for portfolio optimization. Applications include a mixture of data from daily data to high-frequency microstructure data for a variety of asset classes. Throughout, they include illustrative code examples and provide a dedicated GitHub repository with detailed implementations.
Log in to write a review for this book.
No reviews yet. Be the first to share your opinion.
Biography not available.
Biography not available.